
Keep your existing interest rate and loan term while potentially reducing your monthly mortgage payment.
A mortgage recast offers eligible homeowners a way to lower their monthly principal and interest payments without replacing their current mortgage. By making a substantial payment toward your outstanding loan balance, you may be able to reduce your monthly payment while maintaining the interest rate and remaining term you already have.
Loan availability and terms depend on borrower and property qualifications.
Start with the life you want to build.
What Is a Mortgage Recast?
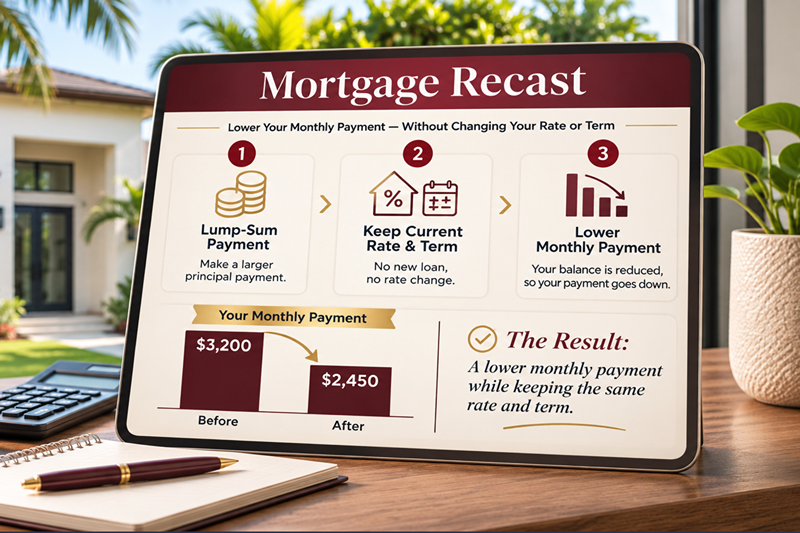
A mortgage recast, also known as re-amortization, allows eligible homeowners to recalculate their monthly mortgage payments after making a significant lump-sum payment toward their loan principal.
Unlike refinancing, which replaces your existing mortgage with a new loan, recasting adjusts your payment schedule based on the reduced balance. Your existing interest rate and remaining loan term stay the same, but your monthly principal and interest payment decreases.
For homeowners who want greater monthly financial flexibility without giving up a favorable mortgage rate, recasting can be an attractive option.
How Does a Mortgage Recast Work?
The process is generally straightforward:
- Confirm Eligibility: Contact your mortgage servicer to determine whether your existing loan qualifies for recasting.
- Reduce Your Principal: Make a qualifying lump-sum payment toward your outstanding mortgage balance.
- Recalculate Your Payments: Your mortgage servicer re-amortizes the remaining balance over the existing repayment period.
- Enjoy Lower Monthly Payments: Once approved and processed, your new principal and interest payment takes effect without changing your existing interest rate or remaining loan term.
Key Benefits of a Mortgage Recast
Lower Monthly Payments
Reduce your monthly principal and interest obligation, potentially freeing up cash flow for other financial priorities.
Keep Your Existing Interest Rate
Maintain your current mortgage rate, particularly valuable if it’s lower than rates available today.
Avoid a Full Refinance
Recasting generally involves less paperwork and lower processing costs than obtaining a new mortgage.
Reduce Long-Term Interest Costs
By lowering your outstanding principal balance, you may reduce the total interest paid over the remaining life of your loan.
Who Should Consider a Mortgage Recast?
A mortgage recast may be particularly beneficial for homeowners who:
- Have received a financial windfall, bonus, inheritance, or proceeds from selling another property.
- Want to reduce monthly mortgage payments without refinancing.
- Have an attractive existing interest rate they prefer to preserve.
- Want to improve monthly cash flow while maintaining their current mortgage structure.
- Have sufficient available funds to make a substantial principal payment.
Mortgage Recast vs. Refinancing: What’s the Difference?
While both options can help homeowners adjust their mortgage payments, they serve different financial objectives.
| Mortgage Recast | Mortgage Refinance |
|---|---|
| Retains your existing mortgage | Replaces your mortgage with a new loan |
| Keeps your current interest rate | May provide a different interest rate |
| Maintains the remaining loan term | May change the loan term |
| Requires a qualifying principal reduction | Does not necessarily require a lump-sum payment |
| Typically involves lower fees | Generally involves closing costs |
The right strategy depends on your current mortgage, available funds, and long-term financial goals.
Mortgage Recast Eligibility and Requirements
Not all mortgages qualify for recasting. Eligibility is determined by your mortgage servicer and the applicable loan investor or program.
Common considerations include:
- Loan Type: Conventional loans are typically eligible; certain jumbo loans may qualify. FHA, VA, and USDA loans generally do not qualify for standard recasting.
- Principal Payment: A minimum lump-sum principal reduction may be required.
- Payment History: Your mortgage typically must be current and in good standing.
- Processing Fees: Some mortgage servicers charge a modest administrative fee.
- Servicer Approval: Final eligibility, timing, and requirements depend on the company servicing your loan.
A recast reduces the principal and interest portion of your payment. Property taxes, homeowners insurance, and other escrow-related expenses may remain unchanged or fluctuate independently.
Frequently Asked Questions
Does a mortgage recast change my interest rate?
No. A standard mortgage recast preserves your existing interest rate while recalculating payments based on your reduced principal balance.
Does a mortgage recast shorten my loan term?
No. Your remaining loan term generally stays the same. Recasting is primarily designed to lower your required monthly principal and interest payment.
How much money do I need to recast my mortgage?
Minimum principal payment requirements vary by mortgage servicer and loan program. Some require a specific dollar amount, while others require a percentage of the outstanding loan balance.
Can I recast an FHA or VA mortgage?
FHA and VA loans generally are not eligible for standard mortgage recasting. Eligibility should always be confirmed with your mortgage servicer.
Is recasting better than refinancing?
Not necessarily. Recasting may be more attractive when you want to preserve an existing low interest rate, while refinancing may be worth exploring if you want to change your rate, loan term, or other financing features.
Make Your Mortgage Work Smarter For You.
At The Boucaud Team, we believe your mortgage strategy should evolve with your financial goals. Whether you’re exploring a mortgage recast, refinancing, or another financing solution, our team can help you understand your options and make informed decisions with confidence.
The content provided within this website is presented for information purposes only. This is not a commitment to lend or extend credit. Information and/or dates are subject to change without notice. All loans are subject to credit approval. Other restrictions may apply. Not affiliated with or endorsed by HUD/FHA, the VA, USDA, or any government agency. Renovation financing is subject to eligible improvements, contractor approval, inspections, and completion deadlines.